What Happens if My Ex Stops Paying the Mortgage?

Dated: May 12 2026

Views: 25

Missing just one mortgage payment during a separation can quickly turn into a much larger financial issue.

A common and risky mistake many separating couples make is assuming the following:

“If they move out, the mortgage becomes their problem, or mine.”

But lenders usually do not see it that way.
If both people signed the original mortgage, they are usually both still legally responsible for the debt until one of the following happens:
  • The property is sold,
  • The mortgage is refinanced,
  • Or one person is formally removed from the loan.
So if payments stop, the bank typically does not care who agreed to pay during the separation. The lender just sees missed payments linked to both people on the mortgage.
Before we continue, please remember this article is for general information only and is not legal or financial advice. Every separation is unique, so if you are dealing with missed mortgage payments, talk to a lawyer, lender, or financial professional about your own situation.
One of the first things to know is that missed mortgage payments can affect your credit very quickly.
Equifax Canada says that payment history is one of the biggest factors in your credit score. Missing even one payment can start to affect your ability to borrow in the future.
This is especially important during separation, since many people will soon need to:
  • Refinance,
  • Qualify for a new mortgage,
  • Rent another property,
  • Obtain financing,
  • Or rebuild financially on a single income.
I have seen cases where just one missed payment during a separation made it harder for someone to buy another home months later.
People also often underestimate how fast financial stress can grow when communication breaks down.
At first, the problem might seem temporary:
“They’re just late this month.”
But prolonged missed payments can eventually lead to:
  • Arrears,
  • Collection calls,
  • Legal action,
  • Refinancing difficulties,
  • Or forced sale pressure.
At the same time, the home can start to suffer financially as well. Repairs may be delayed, maintenance can be missed, and tension often grows over spending. When the property goes up for sale, buyers may notice this instability.
According to the Financial Consumer Agency of Canada, homeowners struggling with mortgage payments should communicate with lenders as early as possible. Waiting too long generally reduces available options.
This advice is even more important during separation, since people often avoid talking about money when emotions are high.
One of the biggest mistakes I see is separating couples relying only on verbal agreements.
For example:
“He said he’d keep paying.”
“She said she’d reimburse me later.”
“We agreed I’d cover things until the house sold.”
The problem is that stress can change people. Financial pressure can change people. Separation can also change timelines.
That is why having written agreements is so important.
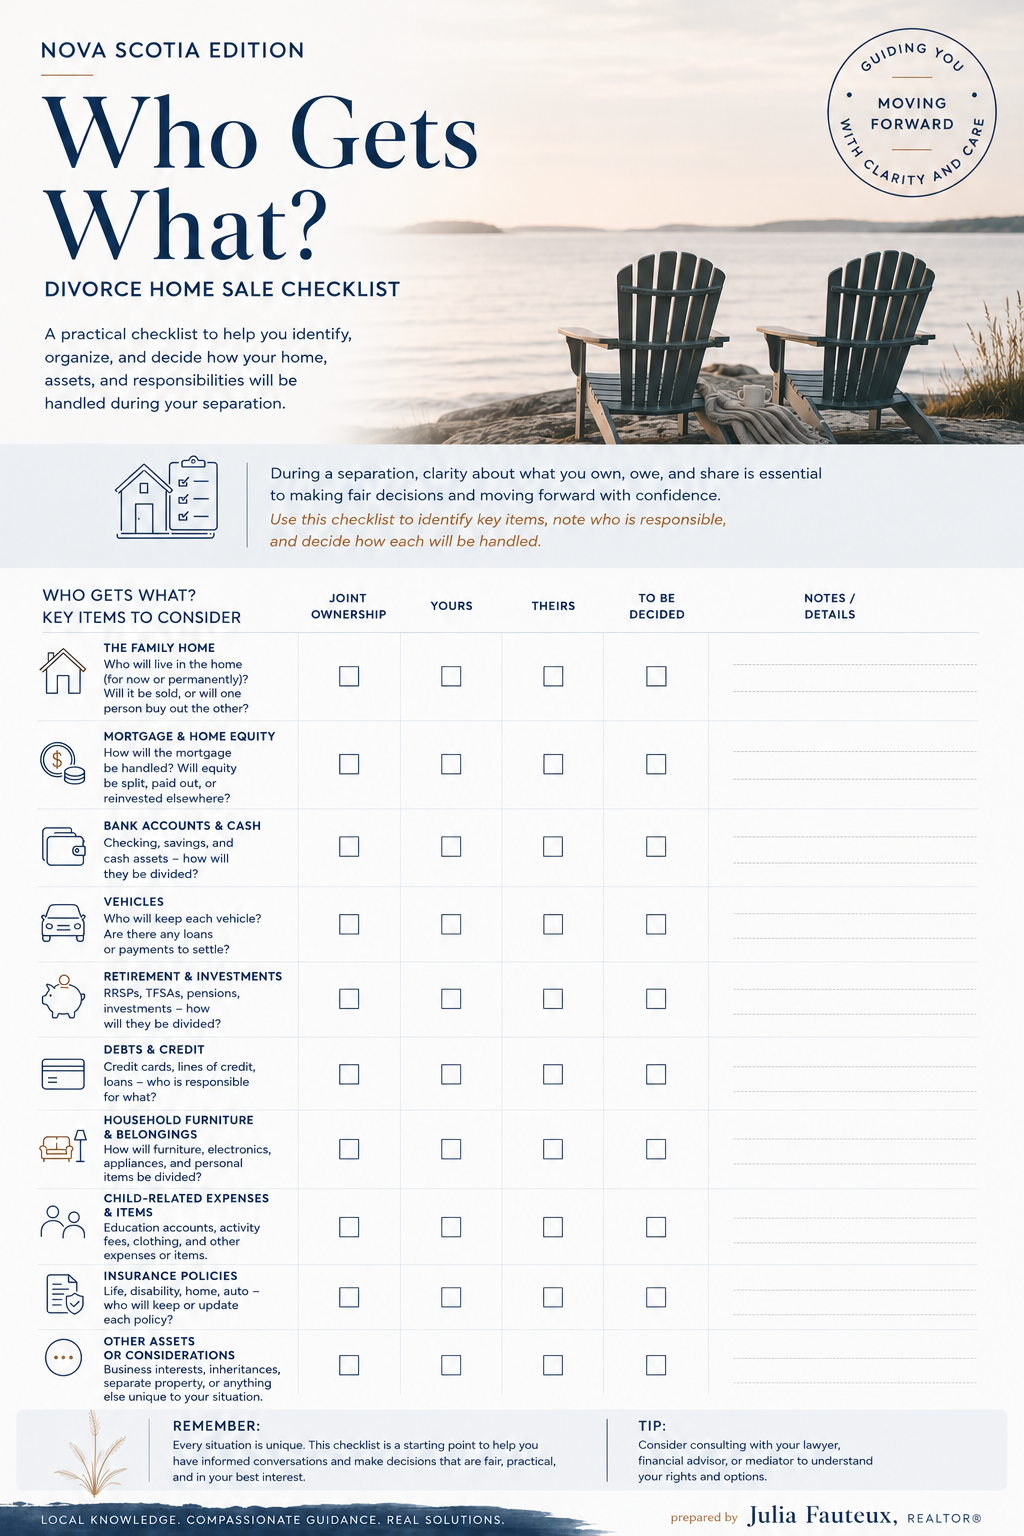
Even relatively amicable separations benefit from written clarity surrounding:
  • Mortgage obligations,
  • Utility responsibilities,
  • Reimbursement expectations,
  • Listing timelines,
  • And what happens if the home does not sell quickly.
Without a clear structure, uncertainty can end up costing a lot.
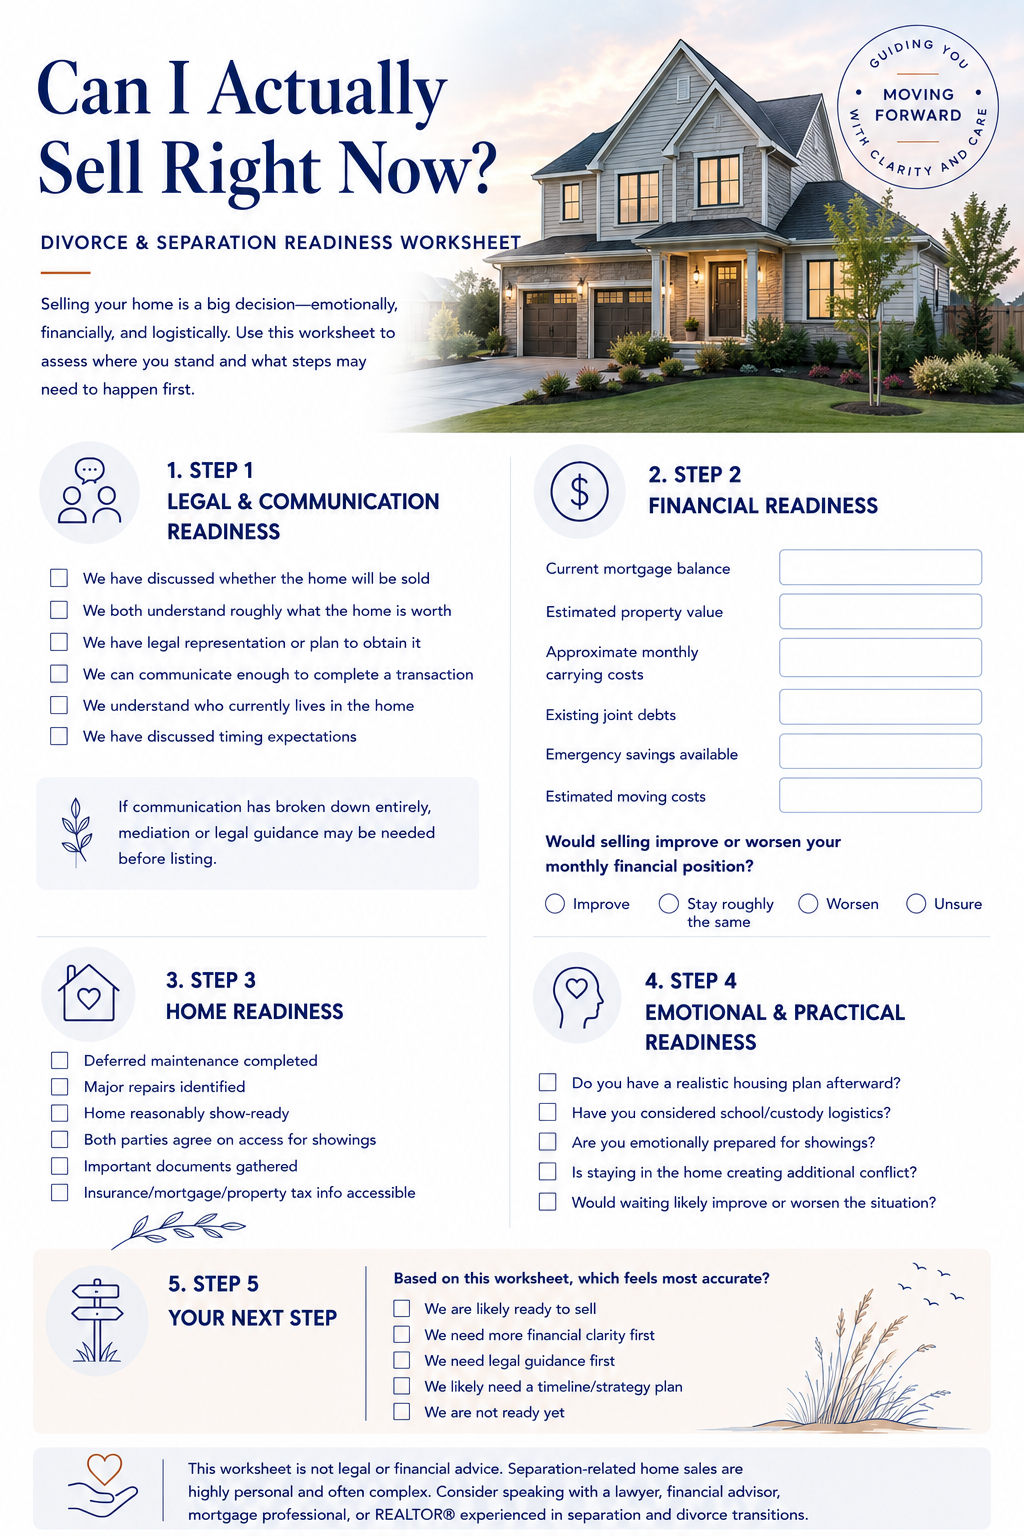
If you are already having trouble making payments, there are a few practical steps you should take as soon as possible.
First, gather clear information:
  • Whose name is on the mortgage,
  • What the monthly obligations actually are,
  • Whether there are penalties or arrears,
  • And whether refinancing is realistic.
Second, talk to professionals sooner rather than later. Depending on your situation, this could include:
  • A lawyer,
  • Your lender,
  • A mortgage broker,
  • An accountant,
  • Or a REALTOR® familiar with separation-related sales.
Third, try not to make housing decisions based only on emotion or panic. I have seen people use up their savings, take on high-interest debt, or put off important decisions because they hoped things would settle down emotionally first.
Unfortunately, lenders operate on timelines, not emotions.
This is especially important in Nova Scotia right now, since carrying costs have gone up a lot in recent years. Higher interest rates, insurance, utilities, and maintenance can make a home that was affordable on two incomes suddenly feel overwhelming after a separation.
According to the Bank of Canada mortgage tools and resources, even moderate increases in borrowing costs can significantly affect affordability over time. Many separating couples are now facing refinance scenarios at rates far higher than when they originally purchased together.
This financial reality can force people to make decisions quickly.
I often remind clients of this:

Protecting your credit during separation matters almost as much as protecting your equity.

Because long after the relationship itself is over, damaged credit can continue affecting:
  • Future housing,
  • Borrowing ability,
  • Vehicle financing,
  • And overall financial flexibility.
The sooner you deal with the risk of missed payments, the more options you will usually have.

Final Thoughts

When one spouse stops helping with the mortgage, the problem is rarely just about the payment. It is often tied to stress, fear, financial pressure, poor communication, or not knowing what will happen next.
But ignoring the problem almost never makes it better.
The earlier separating couples understand:
  • Who remains legally responsible,
  • What financial risks exist,
  • And what realistic options are available,
It becomes much easier to make proactive choices rather than wait for a crisis.
If you need help understanding what a property situation after separation might look like in Nova Scotia, I am always happy to have a private conversation.
Blog author image

Julia Fauteux

Buying or selling a home is more than a transaction—it’s a major life move, and having the right strategy makes all the difference. I’m Julia Fauteux, a REALTOR® based in Nova Scotia, helping ....

Latest Blog Posts

Halifax vs. Cape Breton: What Changes When You Trade City Access for Island Life?

People often talk about moving to Cape Breton as if the whole island offers the same way of life.It doesn’t.Living in Sydney is quite different from living near Inverness, Chéticamp,
Read More

Halifax vs. Annapolis Valley: Which Lifestyle Fits Your Move?

If you’re moving to Nova Scotia, one of the first decisions you’ll need to make is whether you want to live in Halifax or outside the city.The Annapolis Valley is a popular option,

Read More

Can You Help Me Figure Out Where I Should Live Before I Start Looking at Homes?

Can You Help Me Figure Out Where I Should Live Before I Start Looking at Homes?(3 Min Read, OR jump to the "Where To Live in Nova Scotia" quiz here.)Absolutely.Actually, many of my relocation

Read More

What Surprises Newcomers Most After They Move to Nova Scotia?

Most people have a particular reason for moving to Nova Scotia.Sometimes it’s a job opportunity.Sometimes it’s family.Sometimes it’s retirement.Sometimes it’s simply the

Read More